
NPS Death Claim: How Nominees and Legal Heirs Claim the Corpus
A woman in Pune found out her husband held a National Pension System (NPS) account only while going through his papers after his death. The pension records showed a nominee, but her brother-in-law insisted the money should be split among all the legal heirs instead. Nobody in the family knew which claim was correct, or where to even start.
Cases like this are common, because an NPS death claim depends on two separate things: who was named as nominee, and what the law actually lets a nominee keep. This blog covers who can claim the corpus, the documents and steps involved, how the payout splits between lump sum and annuity, and how it is taxed. AasaanWill can help families through exactly this kind of confusion when a Will or nomination record is unclear.
Key Highlights
On a subscriber’s death, the entire NPS corpus becomes payable, first to the registered nominee and then to legal heirs if no nominee was named.
The claim is filed with the Point of Presence (POP) where the account was opened, or started online using the subscriber’s PRAN details.
A nominee usually receives the payout first but may still need to pass it on under succession law if there is no Will.
Government sector subscribers with a corpus above five lakh rupees must put at least 80 percent into a default annuity for dependents.
Non-government subscribers face no mandatory annuity requirement on death.
The death benefit paid to a nominee or legal heir is exempt from income tax.
Keeping nomination and KYC details updated is the single biggest factor in how quickly a death claim settles.
Who Can Claim the NPS Corpus After a Subscriber’s Death?
The registered nominee is entitled to the payout first. If no nominee was recorded, or the nominee has also died, the claim passes to the subscriber’s legal heirs instead.
Subscribers can register up to three nominees, each assigned a percentage share of the corpus. If the subscriber updated the nomination after marriage, divorce, or the birth of a child, the payout follows whichever record was last updated, not what the family assumes was intended. Where there is no nominee, the claimant generally needs a legal heir certificate or succession certificate to show who is entitled and in what share.
Being named a nominee does not automatically make someone the final owner of the money under Indian succession law. A nominee is generally expected to receive the payout and then pass it on according to the deceased’s Will, unless the scheme rules say otherwise.
For a closer look at how this works, AasaanWill’s guide on nominee and legal heir rights in India breaks down when a nominee is only a custodian and when they are the final owner.
How Is the NPS Death Claim Process Started?
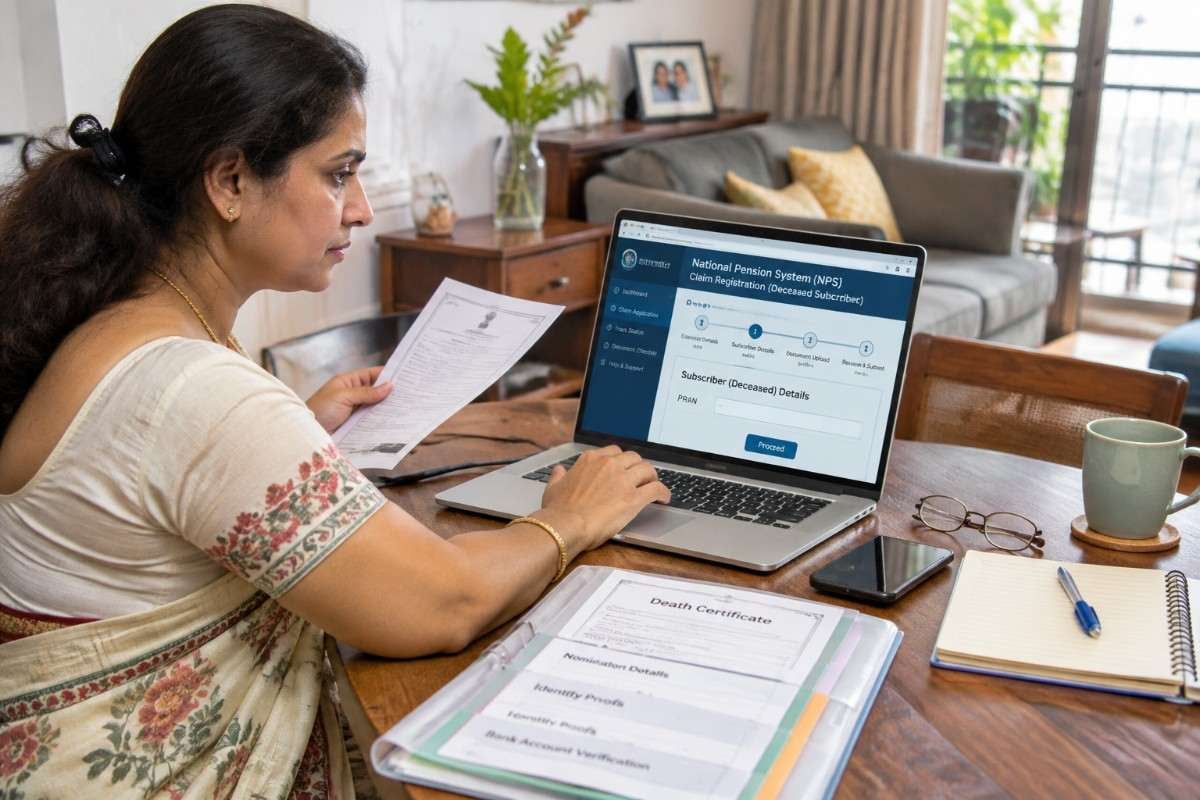
A nominee or legal heir can start the claim online using the subscriber’s PRAN details, or submit a physical form at the POP where the account was opened. The process generally runs as follows once a death certificate is available:
Register as claimant. The claimant logs into the NPS portal and registers a claim against the deceased subscriber’s PRAN, or hands a physical withdrawal form to the POP.
Verification. The POP, or the relevant nodal office for government employees, checks the claimant’s identity, the death certificate, and the supporting documents.
Authorisation. Once satisfied, the POP authorises the withdrawal and raises it on the claimant’s behalf if it was not already submitted online.
Payout. The corpus is credited electronically to the bank account the claimant provided while registering the claim.
Status check. Progress can be tracked through the withdrawal status view after logging in, without needing a separate claim ID for most death cases.
What Documents Are Needed for an NPS Death Claim?
A death claim needs the subscriber’s death certificate, a withdrawal form, and proof of the claimant’s identity, address and bank account, along with nomination or legal heir proof depending on who is claiming. The exact list can vary slightly by POP, but generally includes:
The subscriber’s death certificate, issued by the municipal authority.
The withdrawal form for a claim due to the death of a subscriber.
The subscriber’s PRAN card or PRAN details.
Proof of identity and address for the claimant, such as Aadhaar, PAN, or a passport.
Bank account proof, usually a cancelled cheque or statement showing the account number and IFSC code.
Proof of nomination, where a nominee is claiming, or a legal heir certificate or succession certificate where legal heirs are claiming instead.
In some cases, an indemnity bond or no-objection letter from other heirs, where one heir claims on behalf of several.
Is the NPS Corpus Paid as a Lump Sum or an Annuity?
This depends on the subscriber’s sector and the size of the corpus.
Government sector: If the accumulated pension wealth is five lakh rupees or less, the entire amount is paid as a lump sum, though the nominee can still choose an annuity voluntarily. Above five lakh rupees, at least 80 percent must go towards a default annuity for the subscriber’s dependents, typically the spouse, then children or parents if there is no surviving spouse. The remaining 20 percent is paid as a lump sum. Where no dependents survive, the annuity portion instead goes to surviving children or, failing that, the legal heirs.
Non-government sector: There is no mandatory annuity on death. The entire corpus can be paid as a lump sum to the nominee or legal heir, who may still choose an annuity if a regular income is preferred over a one-time payout. The official NPS exit rules set out these thresholds for both sectors.
Is the NPS Death Benefit Taxable?
No. The amount paid to a nominee or legal heir on a subscriber’s death is exempt from income tax under the provisions notified for NPS death benefits. This differs from the tax treatment on a subscriber’s own retirement withdrawal, where only part of the lump sum is tax-free. Families should still keep the claim documents and payout confirmation safely, since a bank may later ask for proof of the source of funds.
What Should Families Do to Avoid Delays in an NPS Death Claim?
Delays usually come down to outdated nomination details or mismatched KYC, not the claim process itself.
Update the nomination after every major life event, such as marriage, divorce, or the birth of a child, since the claim follows whoever is on record.
Record intentions clearly in a Will, especially where other dependents or heirs might otherwise dispute how the payout should be shared. A registered Will alongside a current nomination removes most of this doubt.
Start the claim soon after the death certificate is issued, since bank account changes or missing signatures can add weeks to an already slow process.
Check the claimant’s bank and identity documents in advance, so the POP does not reject the application over mismatched KYC.
Check whether the subscriber held a Tier II account, since it is redeemed automatically alongside Tier I and should show up in the final settlement.
How AasaanWill Helps
Sorting out an NPS death claim often means untangling nomination records, legal heir paperwork, and family expectations all at once. Our team assists with:
Drafting a clear Will that specifies how pension payouts and other assets should be shared among family members.
Guiding families through obtaining a legal heir certificate or succession certificate where no nominee survives.
Advising on how to align NPS nominations with a Will so the two do not contradict each other.
Supporting families through the broader estate settlement process once a death claim is underway.
Conclusion
An NPS death claim comes down to one question: who is on record as the nominee, and if nobody is, who the legal heirs are under succession law. Filing it needs a death certificate, identity and bank proof, and either nomination or legal heir documents, submitted through the POP or online. AasaanWill can help families put a Will and NPS nomination in order together, so the right person receives the payout without a family dispute along the way.
Frequently Asked Questions
1. Who can claim the NPS corpus after a subscriber’s death?
The registered nominee is first in line. If there is no nominee, the subscriber’s legal heirs can claim the corpus by providing a legal heir certificate or succession certificate.
2. Can more than one nominee be registered for an NPS account?
Yes, a subscriber can register up to three nominees, each assigned a specific percentage share of the corpus.
3. What happens if the subscriber never registered a nominee?
The claim is treated as a legal heir claim. The claimant needs a legal heir certificate, succession certificate, or letter of administration to establish entitlement.
4. Is an annuity compulsory when an NPS subscriber dies?
Only for government sector subscribers with a corpus above five lakh rupees, where at least 80 percent must go into a default annuity. Non-government subscribers face no such requirement.
5. How is the NPS death claim amount paid out?
It is credited electronically to the bank account the claimant provided while registering the claim.
6. What is the first step to filing an NPS death claim?
The nominee or legal heir registers as a claimant online using the subscriber’s PRAN details, or submits a physical withdrawal form at the POP where the account was opened.
7. Does the claimant need a separate claim ID to start the process?
No, most death claims do not require a separate claim ID, unlike a standard retirement withdrawal.
8. Is the NPS death benefit taxable?
No, the amount paid to a nominee or legal heir on the subscriber’s death is exempt from income tax under the provisions notified for NPS.
9. What happens to a Tier II account if the subscriber dies?
It is redeemed automatically and paid out together with the Tier I death benefit, since Tier II cannot stay active without an active Tier I account.
10. Can a nominee be asked to share the NPS payout with other family members?
A nominee usually receives the money first, but under general succession law they may still be expected to distribute it according to the deceased’s Will, unless specific scheme rules say the nominee keeps it outright.
11. How long does an NPS death claim usually take to settle?
Timelines vary by POP, but claims with accurate KYC and a clear nomination generally settle faster than legal heir claims needing extra certificates.
12. What bank proof does the claimant need to submit?
Proof such as a cancelled cheque or bank statement confirming the account number and IFSC code in the claimant’s name.
13. Can a legal heir claim the NPS corpus if a nominee is still alive?
Generally, the registered nominee is paid first. If there is a Will and the nomination matches the Will, the nominee gets to keep the NPS corpus. A legal heir can only claim directly if there is no surviving nominee, or the nominee has also died.
14. Can AasaanWill help with an NPS death claim?
AasaanWill does not process claims with the pension authority, but it helps families obtain the legal heir or succession certificate needed, and drafts a Will that clarifies how pension proceeds should be shared.
15. What should families do now to make a future NPS claim easier?
Keep the nomination updated after major life events, ensure KYC details are current, and record clear intentions in a Will alongside the nomination.
Disclaimer:
This article is for general informational purposes only and does not constitute legal advice. The information presented reflects the law as of the date of publication. For advice on your specific situation, please consult a qualified advocate.
“If your family is dealing with an NPS nominee or legal heir claim, talk it through with AasaanWill. Get started with AasaanWill today. “
Get in touch with us
Not sure about anything? We are just one phone call away. Book a free 15 minute consultation.

+91-8764447848
+91-8919084868

+91-8764447848
+91-8919084868
AasaanWill’s Privacy Commitment to you
We never use your data without your consent, or sell it to a third party.